Alternative investments vs traditional investments: what’s the difference?
ANote Music
September 11, 2026
12 min read
Alternative investments differ from traditional investments not only in the assets involved, but also in how they are accessed, the legal and economic rights an investor acquires, how potential returns can arise, how they are valued and how an investor can exit the position.
This article explains these differences, outlines common types of alternative investments and sets out factors that can be considered when evaluating an alternative investment.
What are alternative and traditional investments?
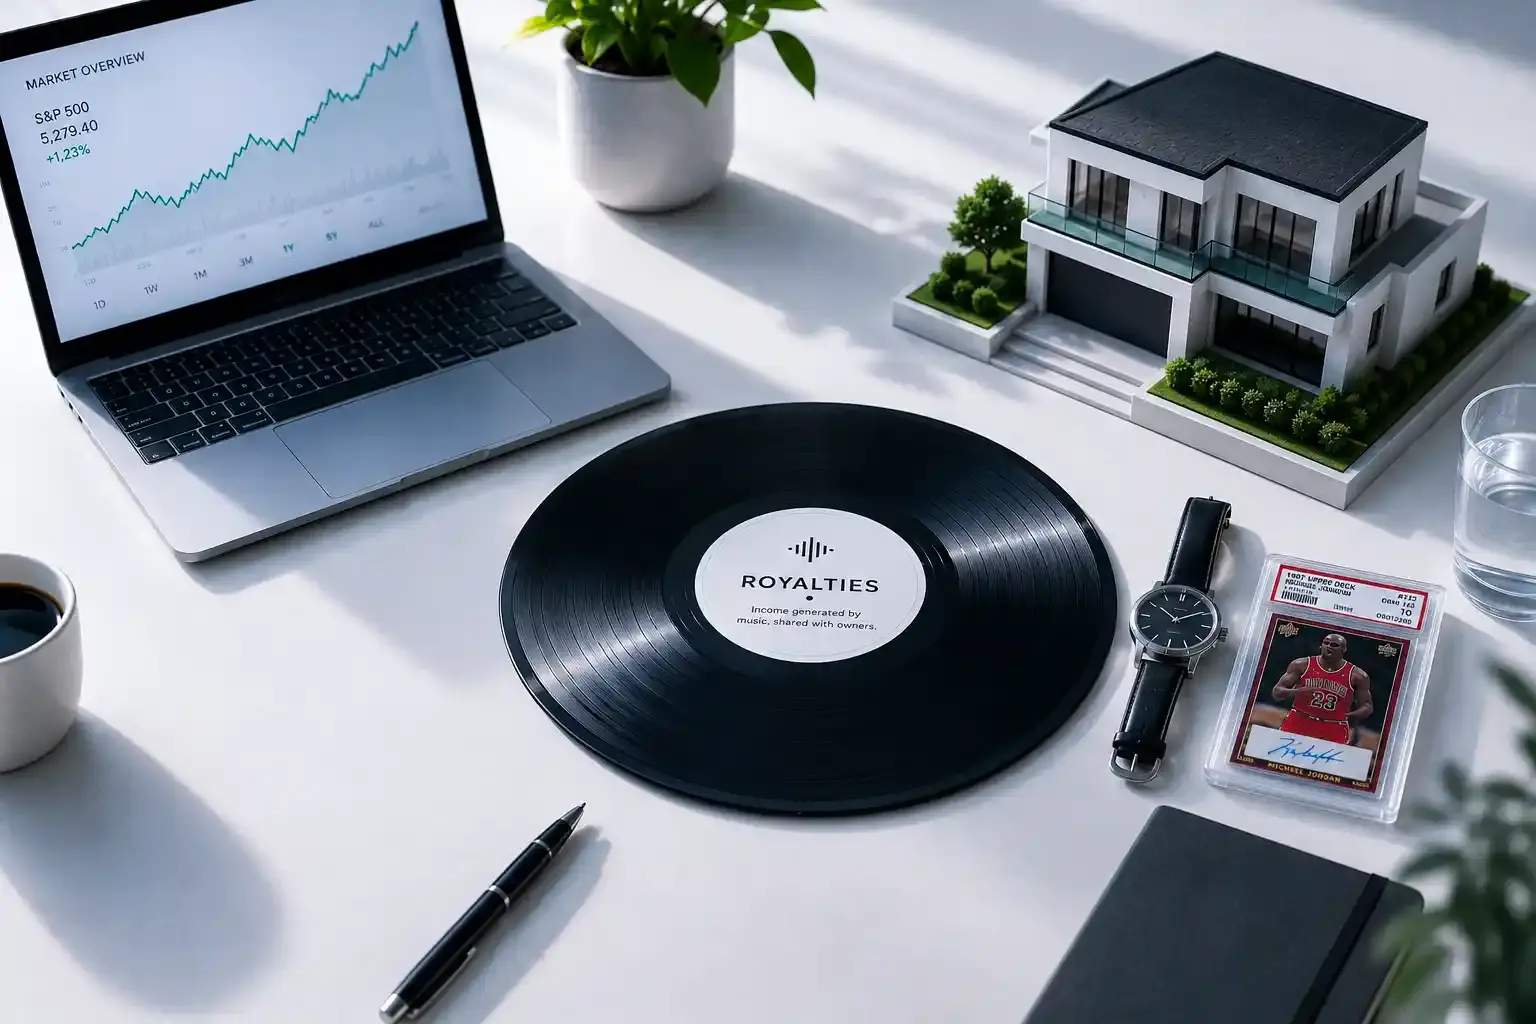
Traditional investments generally include established asset classes such as listed equities, bonds and cash or cash equivalents, together with funds that invest primarily in these assets. Alternative investments generally comprise assets and investment strategies outside these conventional categories.
They are commonly accessed through private markets, specialist funds or marketplaces, although some alternative exposures are also available through publicly traded instruments.
Common types of alternative investments
Alternative investments cover a broad range of assets, strategies and investment structures. Common types include:
- Real estate. Direct property investments or pooled property vehicles, with potential returns arising from rental income, changes in capital value, or both.
- Private equity. Investments in privately held companies, commonly made through specialist funds or other private-market structures.
- Hedge funds. Pooled investment vehicles that can pursue a broad range of strategies and may use techniques such as short selling, derivatives and borrowing.
- Commodities. Assets such as metals, energy products and agricultural commodities, which can be accessed directly or through financial instruments such as futures and other derivatives.
- Art and collectibles. Physical assets such as artworks and collectible items, whose value can rise or fall and which can involve costs such as storage, insurance and transaction fees.
- Private credit. Lending provided outside traditional bank financing and public debt markets, with potential returns typically arising from contractual interest payments.
- Royalty and intellectual property interests. Contractual or proprietary rights linked to income generated from the use of intellectual property, including music catalogue royalties, film and television rights, patents and certain licensing or franchise rights.
How do alternative and traditional investments work differently?
The differences between traditional and alternative investments can be considered across several practical dimensions, including access, the rights acquired, sources of potential return, valuation, available information, liquidity and regulation. The table summarises these dimensions, with each explained in more detail below.
How do you access an alternative investment?
Traditional investments are commonly accessed through brokers, investment funds and established public markets. Alternative investments are often accessed through private placements, specialist funds, marketplaces or other investment structures, some of which may be subject to investor eligibility requirements.
Specialist marketplaces and fractional structures have also broadened retail access to certain alternative assets. Access nevertheless depends on the specific asset, investment structure and jurisdiction.
What does the investor actually acquire?
Traditional investments can give an investor an ownership interest, a debt claim or an interest in an investment fund. Alternative investments can involve a physical asset, an interest in a fund or other vehicle, or a contractual entitlement to an income stream.
With listed equities, the investor acquires an ownership interest in a company. With bonds, the investor holds a debt claim with rights defined by the terms of the instrument. With an investment fund, the investor holds an interest in the fund rather than direct ownership of each underlying asset.
Alternative investments are less standardised, with the legal and economic rights acquired depending on the asset, structure and terms of the specific investment. Two investments linked to similar underlying assets may therefore provide different rights, cash-flow entitlements, durations or exit mechanisms.
For that reason, understanding the rights attached to an alternative investment can be as important as understanding the asset category itself.
How are returns generated?
Potential returns from traditional investments can arise from income, changes in market value, or both. Depending on the instrument, this can include dividends, interest payments and gains or losses resulting from price movements.
For alternative investments, the source of potential return depends on the underlying asset together with the structure. Property may generate rental income and changes in capital value, private credit may generate interest income, and royalty interests may generate income from the use of the underlying intellectual property.
These underlying return drivers help explain the factors that can influence an investment’s performance. Property income, for example, can depend on occupancy and rental levels, while royalty income can depend on the use and monetisation of the underlying rights.
Because these drivers can differ from those affecting listed equities or bonds, alternative investments can respond differently to economic and market conditions, so an alternative asset can move on its own timetable. How that sits alongside other holdings depends on the specific asset, and past behaviour is not a guide to future performance.
How are investments valued and priced?
Many listed instruments have observable market prices that can change throughout the trading day. Alternative investments may not have a continuously observable market price. Where this is the case, values may instead be estimated using periodic appraisals or valuation models, while some marketplace-traded investments may have prices established through matched buy and sell orders.
The appropriate valuation method depends on the asset and its structure. Where historical income or performance data is used as an input, it provides evidence of past outcomes rather than a forecast of future performance.
What information is used to evaluate an investment?
Traditional investments are commonly evaluated using regulated disclosures, financial statements and market data. Alternative investments can rely more heavily on asset-level information, historical performance data and transaction-specific documentation, as well as information provided by a fund manager, sponsor or marketplace.
The type, depth and standardisation of the information available can vary by asset and structure, which can make direct comparisons more difficult. Historical performance can inform an assessment, but it does not indicate future results.
How do liquidity and exit work?
Listed instruments generally offer greater liquidity, although liquidity varies by instrument and market conditions. Alternative investments typically offer more limited liquidity, and holding periods can be longer depending on the asset and investment structure.
Exit can be restricted by lock-up periods, fixed fund terms or limited activity in a secondary market. Where a secondary market exists, the ability to sell can depend on buyer demand and the price at which buyers and sellers are willing to transact. The available exit route, any contractual restrictions and prevailing market conditions can therefore all affect how and when an investment can be exited.
How can the risks differ?
Risk depends on the characteristics of the individual investment, including the underlying asset, legal structure and source of potential return. The labels “traditional” and “alternative” do not in themselves determine the type or level of risk.
Alternative investments can involve risks such as limited liquidity, valuation uncertainty, leverage, credit risk or concentration, depending on the asset and structure. Liquidity risk can arise where an investment cannot readily be sold, valuation uncertainty can be greater where values depend on models or appraisals rather than frequent market transactions, and concentration risk can increase where performance depends heavily on a single asset, borrower or income source.
Traditional investments can also involve material risks, including market, credit, interest-rate and liquidity risk, depending on the instrument. Comparing risk therefore requires consideration of the specific characteristics of each investment rather than its category label alone.
What factors can be assessed when evaluating an alternative investment?
Alternative investments can be assessed using a range of considerations that apply to different assets, strategies and investment structures.
- The rights being acquired: whether the investment provides ownership of an asset, an interest in a fund or other vehicle, or a contractual entitlement to income, together with the duration and limitations of those rights.
- The source of potential income or gain: what drives potential income or changes in value, and whether these may arise during the holding period, on exit, or both.
- The historical information available: how much operating or performance history exists, how the information was compiled and whether it allows meaningful comparison.
- The valuation method: what the valuation is based on, how frequently it is updated and who produces or verifies it.
- The costs: any entry, management, transaction and exit charges, and how they are applied.
- The liquidity and exit route: whether a secondary market exists, what conditions may apply to a sale and what happens at the end of any fixed term.
- The investment-specific risks: how the underlying asset, legal structure and source of potential return can affect the risks involved.
These considerations can form part of a broader investment assessment. A longer holding period changes when an asset can be sold, not the risk carried while it is held.
How does music royalty investing work in practice?
Music royalty investing provides a practical example of how an alternative investment can operate. The sections below explain how catalogue investing works on the ANote Music platform.
What does the holder acquire?
On ANote Music, a catalogue share represents a fractional contractual right to a share of future royalty income for the life of the underlying rights or for the term of the listing. It does not confer ownership of the underlying songs, nor equity or debt in ANote Music, a record label or a publisher.
The holder’s rights are therefore defined by the terms of the individual catalogue listing.
How is royalty income generated?
Music royalties are generated when the underlying works are used through channels such as streaming, public performance, broadcast and synchronisation in film, television and advertising.
Royalty income is linked to the use and monetisation of the underlying music rights rather than directly to corporate earnings. Income is variable and is neither fixed nor guaranteed.
What information can be used to assess a catalogue?
Catalogue assessment can draw on historical royalty data, including the amount of income previously generated and the sources from which that income arose.
Song age and its historical decay profile, together with the breadth of usage across territories, platforms and revenue types, can provide additional context. These inputs describe historical performance rather than projected future results.
How are catalogues valued?
ANote values a catalogue by applying a risk-adjusted multiple to historical annualised royalties. The calculation uses the appropriate annualised figure from the previous 12, 24 or 36 months (usually the lowest). The multiple reflects characteristics of the specific catalogue.
The income input is therefore based on historical rather than projected royalties. ANote explains its catalogue valuation process in more detail.
How does liquidity work?
Catalogues are initially made available on ANote Music through primary-market auctions, where participants can bid for catalogue shares. Catalogue shares can subsequently be traded on ANote Music’s secondary market, where prices are established through matched buy and sell orders.
A holder seeking to sell depends on there being sufficient buyer demand at a price they are prepared to accept. A sale is therefore not guaranteed, and the price achieved can be above or below the price originally paid.
This article is provided for general information and educational purposes only. Nothing contained in this article constitutes financial or investment advice, a recommendation or a solicitation to buy, sell or hold any asset, royalty interest or intellectual property right. The information provided does not take into account any individual’s circumstances, objectives, financial situation or risk profile.
ANote Music operates a marketplace for the purchase and sale of royalty interests and/or intellectual property rights. Royalty interests represent contractual rights to receive future music royalty income generated by underlying intellectual property rights and copyrights. Neither music royalties nor royalty interests constitute financial instruments within the meaning of Directive 2014/65/EU on markets in financial instruments (MiFID II).
Purchasing royalty interests and/or intellectual property rights involves risk. Royalty income is variable and is not guaranteed. The value and market price of royalty interests or intellectual property rights may rise or fall, and purchasers may lose some or all of the amounts committed. Where a secondary market is available, liquidity is not guaranteed and holders may not be able to sell their interests immediately or at a particular price.
Any historical performance, royalty distributions, market prices, index data or other historical information referred to in this article is provided for informational purposes only. Past performance is not indicative of future results, and historical relationships or market behaviour should not be interpreted as a guarantee of future performance, returns, liquidity or protection from losses.
Before participating in the ANote Music marketplace, users should ensure that their participation complies with the laws and regulations applicable to them and should independently assess the characteristics and risks associated with the relevant royalty interests or intellectual property rights.